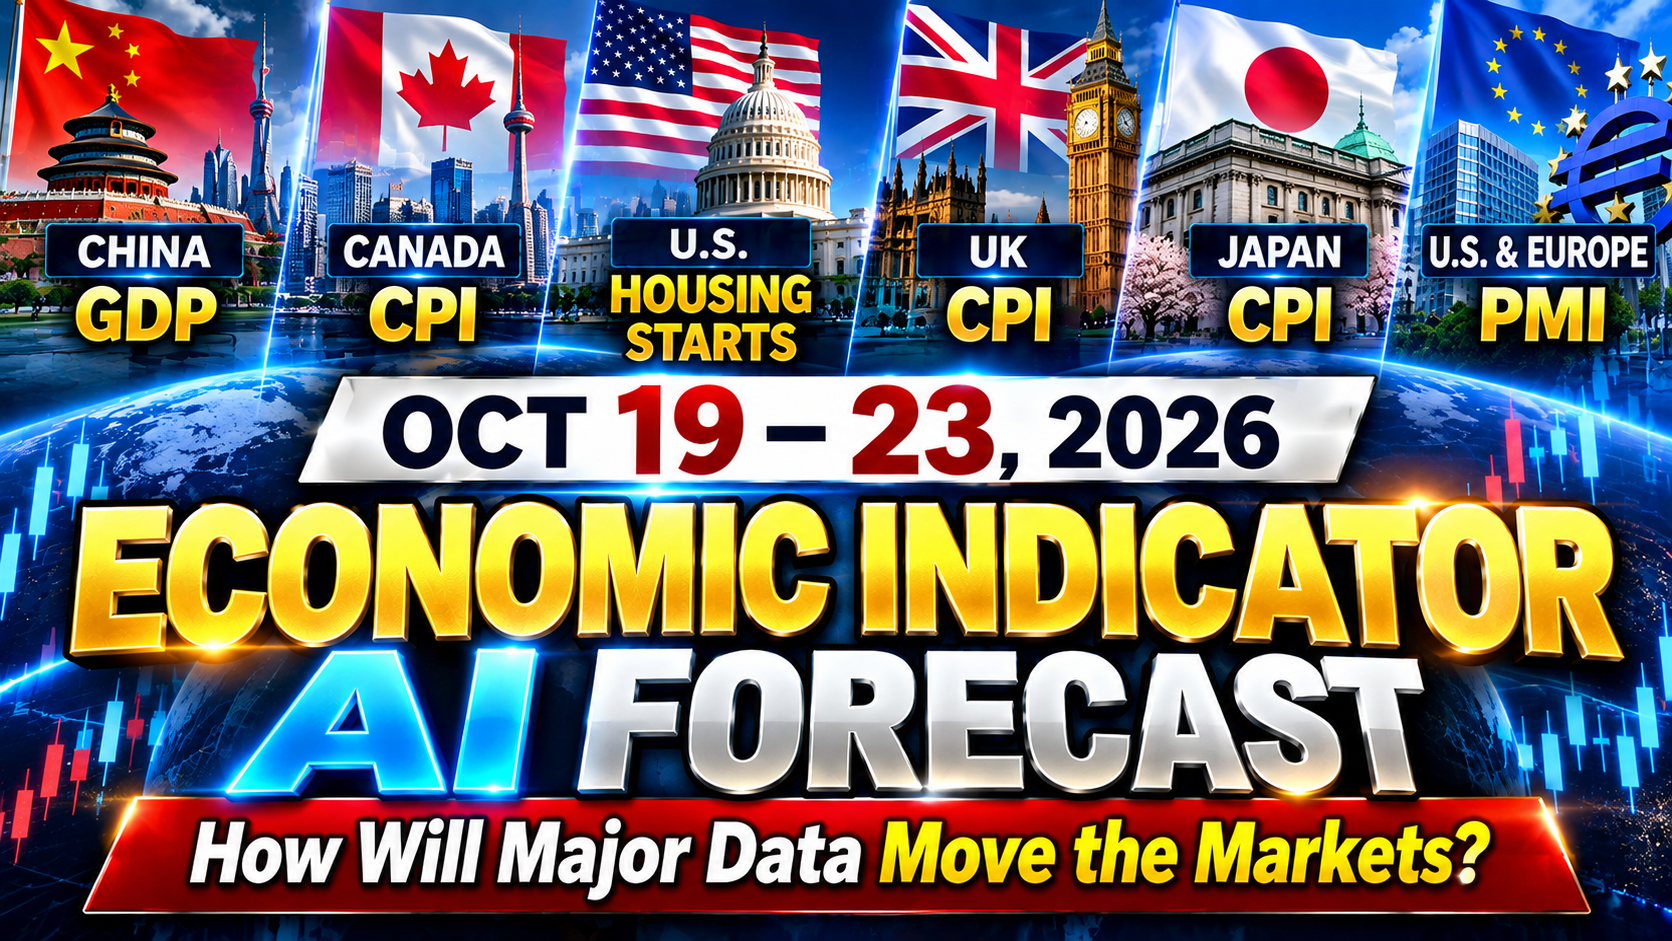
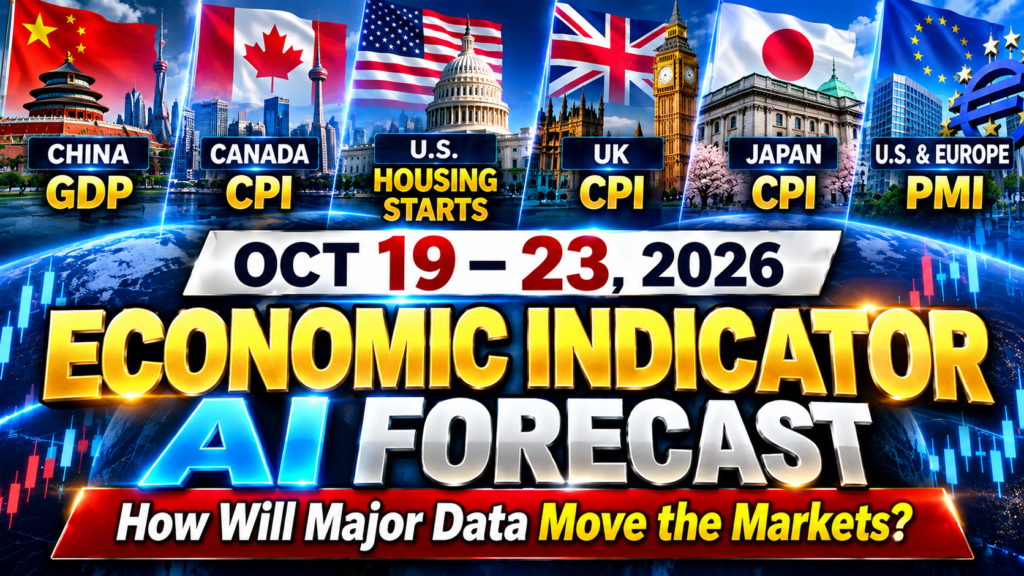
Next week, markets will focus on China’s economic growth, inflation in Canada and the UK, Japan’s CPI, U.S. housing starts, and preliminary business activity data from the United States and Europe.
These releases could influence central bank expectations, bond yields, and currency markets.
All release times below are in UTC (Coordinated Universal Time).
- 🇨🇳 China: Q3 GDP — Is Economic Growth Improving?
- 🇨🇦 Canada: September CPI — Inflation and Interest Rate Expectations
- 🇺🇸 United States: September Housing Starts — Housing Market Strength
- 🇬🇧 United Kingdom: September CPI — Inflation and the British Pound
- 🇯🇵 Japan: September National CPI — Bank of Japan Rate Outlook
- 🌐 United States and Europe: October Flash PMIs — Economic Momentum
- 📝 Weekly Summary
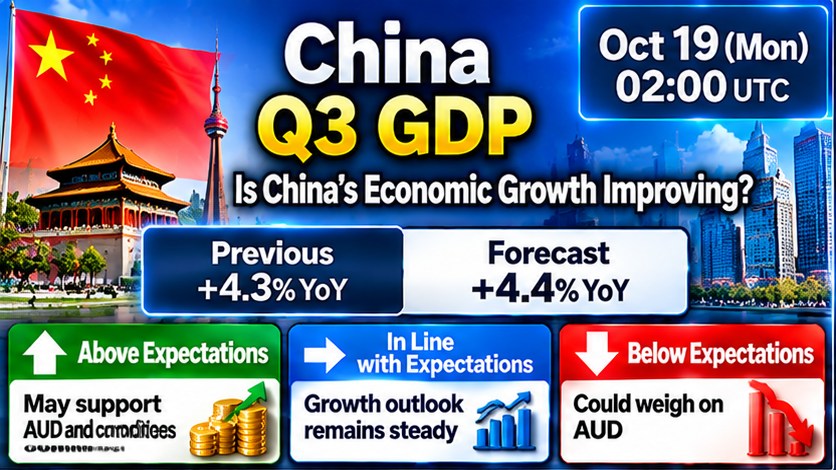
🇨🇳 China: Q3 GDP — Is Economic Growth Improving?
Overview: GDP measures economic growth. Retail sales and industrial production will provide additional insight into domestic demand and manufacturing activity.
Release: October 19, 2026, at 02:00 UTC
Previous: +4.3% year over year
Market Forecast: +4.4% year over year
- 📈 Above expectations: Stronger growth could improve confidence in China’s economy, potentially supporting the Australian dollar and commodity markets.
- 📉 Below expectations: Weaker growth could increase concerns about China’s economy and weigh on the Australian dollar.
- ➡️ In line with expectations: Retail sales and industrial production will help show whether growth is broad-based.
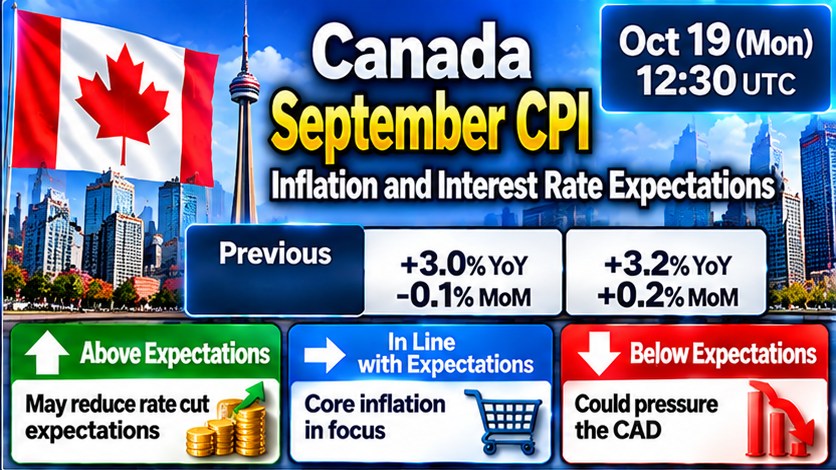
🇨🇦 Canada: September CPI — Inflation and Interest Rate Expectations
Overview: The Consumer Price Index measures changes in consumer prices and is an important indicator for the Bank of Canada’s monetary policy.
Release: October 19, 2026, at 12:30 UTC
Previous: +3.0% year over year; −0.1% month over month
Market Forecast: +3.2% year over year; +0.2% month over month
- 📈 Above expectations: Persistent inflation could reduce expectations for interest rate cuts and support the Canadian dollar.
- 📉 Below expectations: Slower inflation could strengthen expectations for monetary easing and put pressure on the Canadian dollar.
- ➡️ In line with expectations: Core inflation and oil price movements may influence the market reaction.
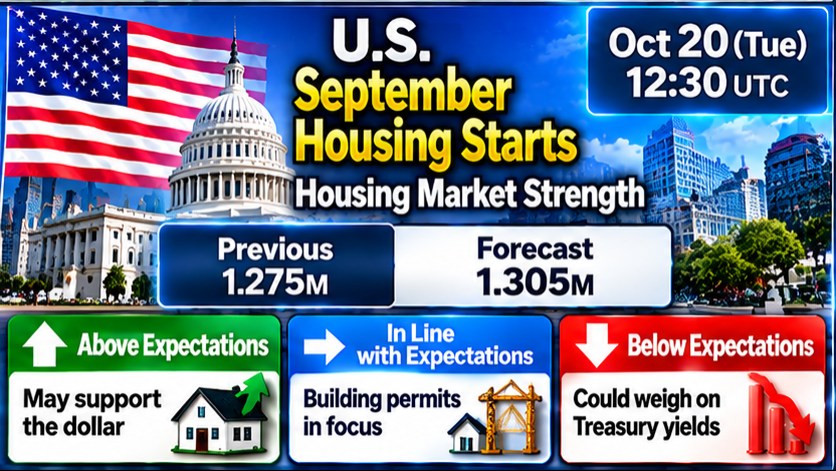
🇺🇸 United States: September Housing Starts — Housing Market Strength
Overview: Housing starts measure the number of new residential construction projects that have begun, providing insight into housing demand and economic momentum.
Release: October 20, 2026, at 12:30 UTC
Previous: 1.275 million units
Market Forecast: 1.305 million units
- 📈 Above expectations: Stronger housing activity could reinforce confidence in the U.S. economy and support the dollar.
- 📉 Below expectations: Weaker activity could raise concerns about growth and potentially push Treasury yields lower.
- ➡️ In line with expectations: Building permits can provide additional clues about future construction activity.
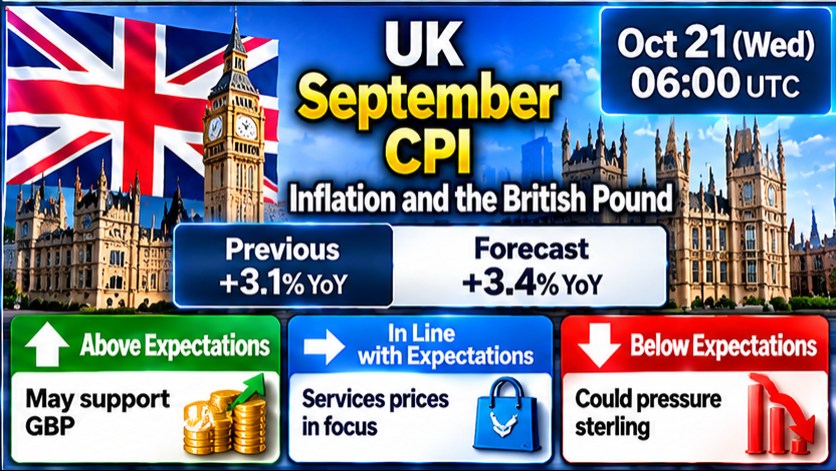
🇬🇧 United Kingdom: September CPI — Inflation and the British Pound
Overview: The Consumer Price Index measures changes in consumer prices. Persistent inflation could influence the Bank of England’s interest rate decisions.
Release: October 21, 2026, at 06:00 UTC
Previous: +3.1% year over year
Market Forecast: +3.4% year over year
- 📈 Above expectations: Stronger inflation could increase expectations for tighter monetary policy and support the British pound.
- 📉 Below expectations: Softer inflation could reduce expectations for tighter policy and put pressure on sterling.
- ➡️ In line with expectations: Core inflation and services prices will help assess how persistent inflation remains.
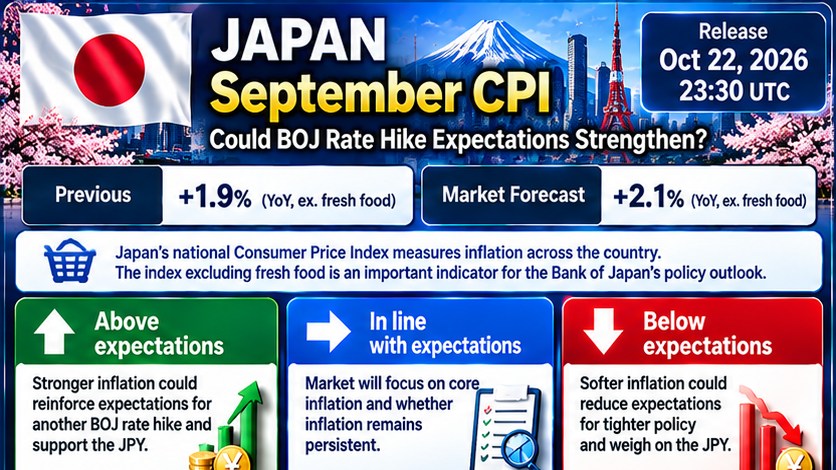
🇯🇵 Japan: September National CPI — Bank of Japan Rate Outlook
Overview: Japan’s national Consumer Price Index measures inflation across the country. The index excluding fresh food is an important indicator for the Bank of Japan’s policy outlook.
Release: October 22, 2026, at 23:30 UTC
Previous: +1.9% year over year, excluding fresh food
Market Forecast: +2.1% year over year, excluding fresh food
- 📈 Above expectations: Stronger inflation could reinforce expectations for another Bank of Japan rate hike and support the yen.
- 📉 Below expectations: Softer inflation could reduce expectations for tighter policy and weigh on the yen.
- ➡️ In line with expectations: The dollar-yen reaction will also depend on U.S. interest rate expectations and the Japan-U.S. interest rate differential.
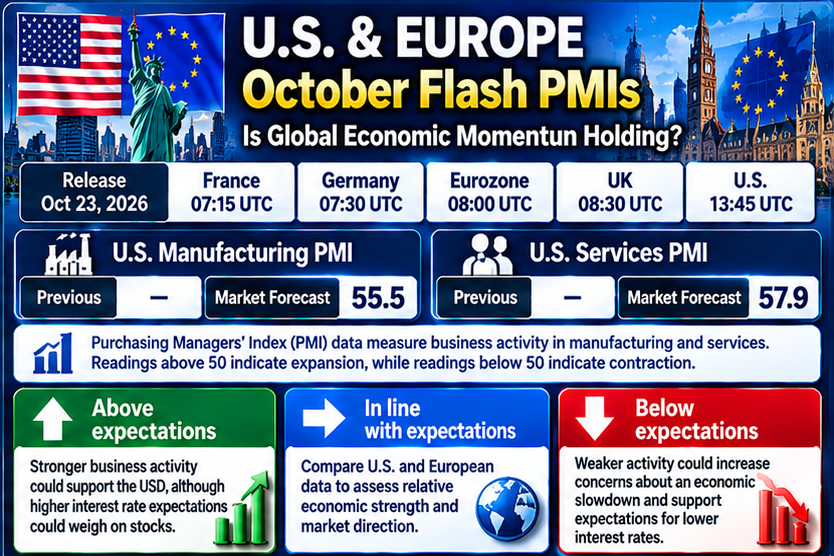
🌐 United States and Europe: October Flash PMIs — Economic Momentum
Overview: Purchasing Managers’ Index data measure business activity in manufacturing and services. Readings above 50 generally indicate expansion, while readings below 50 indicate contraction.
Release schedule: Friday, October 23, 2026 (UTC)
- France Flash PMI: 07:15 UTC
- Germany Flash PMI: 07:30 UTC
- Eurozone Flash PMI: 08:00 UTC
- UK Flash PMI: 08:30 UTC
- U.S. Flash PMI: 13:45 UTC
U.S. Manufacturing PMI — Previous: Not verified
Market Forecast: 55.5
U.S. Services PMI — Previous: Not verified
Market Forecast: 57.9
- 📈 Above expectations: Stronger business activity could support the dollar, although higher interest rate expectations could weigh on stocks.
- 📉 Below expectations: Weaker activity could increase concerns about an economic slowdown and strengthen expectations for lower interest rates.
- ➡️ In line with expectations: Comparing U.S. and European results can help assess relative economic strength and possible currency market movements.
📝 Weekly Summary
The main themes next week are China’s economic growth, inflation in Canada and the UK, Japan’s inflation outlook, and business activity across the United States and Europe.
Compare each release with market expectations and monitor bond yields and currency movements. Even a stronger-than-expected result may have a limited impact if it is already priced into the market.
Watch the data, follow the market reaction, and manage risk carefully.
Note: Market forecasts may change before publication. Verify the latest consensus estimates and official release schedules before trading.